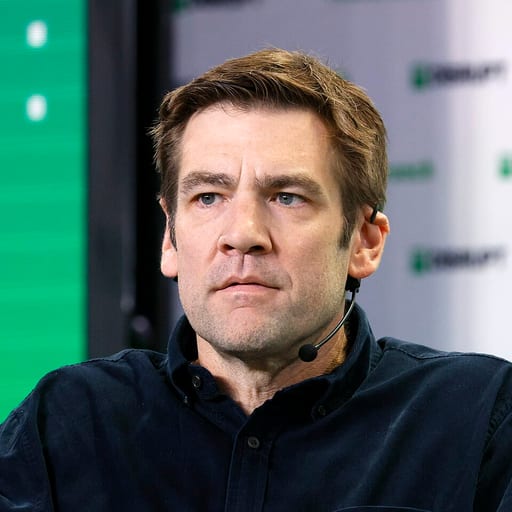
Chris Dixon
크리스 딕슨
General partner at Andreessen Horowitz; founder turned investor
1,416 records in all
- Principles 579
- Episodes 284
- Quotes 553
3 free questions a day, no sign-up.
Quotes
83 basic records of 553
Quotes are word for word from the source.
Monetizing intent
It turns out that knowing people are trying to buy new washing machines or plane tickets to Hawaii is vastly more monetizeable than their names
Our noteDixon argues that purchase intent is more valuable to advertisers than personal identity.
Platform diversity advantage
Platforms tend to provide greater diversity. In the case of e-commerce, the platform approach could also have a price advantage.
Our noteDixon explains why a decentralized platform approach can compete with centralized giants.
Strategic technology outcomes
Basically, if your technology is "too hot" - or, in business-speak, "strategic" or "core" - then there are three likely outcomes
Our noteChris explains the risks of building technology that partners view as too central to their own business.
Defining take rates
The take rate is the percentage of money flowing through the system taken by the network intermediary.
Our noteChris defines the economic metric used to measure platform dominance over creators.
Open Source Advantage
You don't have a hierarchical management structure that can be very efficient. The flip side, and why I think Linux won, is that open-source benefits from what's known as composability
Our noteDixon compares the efficiency of corporate hierarchies with the long-term power of decentralized open-source projects.
Network Effects
At some point, the network effects are so strong that even if you come up with something that's much better, it may just be a challenge.
Our noteDixon discusses the difficulty of displacing established social networks like Facebook.
Legitimate network effects
What I'm hoping is that there're enough legitimate actors around this who create a network effect that, to your point, yes, there will be that stuff, but it will be marginalized.
Our noteDixon talks about how major financial institutions entering crypto will marginalize bad actors.
Human culture advantage
A lot of what we do and a lot of how we think we succeed is, we create a culture in a group of people where entrepreneurs decide they want to work with us.
Our noteChris explains the human element of venture capital that AI cannot easily replace.
Structuring information early
It turns out that imposing even minimal structure on information, especially as it is being created , goes a long way. This is what successful collective knowledge systems do.
Our noteDixon explains why systems like Wikipedia and Google are effective at managing data.
Institutional diversification
the most important form of diversification is across institutions, not, as the experts have told us for decades, across asset classes.
Our noteDixon applies the concept of redundancy to financial management and risk mitigation.
Purpose of Mergers
One of the primary reasons companies merge is to increase bargaining power with respect to buyers and suppliers.
Our noteDixon discusses why companies consolidate to gain leverage in the supply chain.
Perception of industries
From far away, things that are very different look alike. I grew up in a family of musicians and English professors. To them, the entire financial industry seemed corrupt.
Our noteDixon reflects on how outsiders often oversimplify complex industries like finance.
Productivity benefits
Greater productivity and lower prices at least partly compensate for part-time jobs and lower wages.
Our noteHe explains how technological efficiency offsets some of the negative economic impacts on workers.
Profitability of news
The reality is that news is a lousy business. Period. Even Google doesn't make money on it.
Our noteDixon explains why news is not a profitable category even for search giants.
Builders vs Extractors
I think of people who aim to create more value than they capture as "builders" and people who don't as "extractors.
Our noteDixon defines two types of people in the business world based on their value creation.
Analyzing past failures
Entrepreneurs should always ask themselves "why will I succeed where others failed?" If the answer is simply "I'm doing it right" or "I'm smarter," you are probably underestimating your antecedents
Our noteHe warns against arrogance when entering a market where others have failed before.
Understanding emerging economies
I wanted to try to understand this new, emerging economy. It all starts when a user sees an ad on Facebook
Our noteChris Dixon explains the flow of the virtual goods economy in 2009.
Trust in autonomy
Autonomous computers can be relied on and trusted in ways that human-governed computers can't.
Our noteDixon explains why code-governed systems are more reliable than those managed by people.
Disruptive innovation
Wikipedia is a classic example of how the next big thing often starts out looking like a toy.
Our noteDixon reflects on how Wikipedia was dismissed by experts before becoming a global standard.
Means to an end
The tech press is preoccupied with investments, trends, exits, and other "inside baseball" topics. But these are all means to an end.
Our noteHe explains that financial metrics and trends are secondary to the actual products being built.
Logical vs physical
Another way to characterize Shannon's achievement is that he was first to distinguish between the logical and the physical layer of computers.
Our noteHighlighting the importance of separating abstract logic from physical implementation in complex systems.
Difficulty of novelty
The historian Thomas Kuhn once observed that "in science, novelty emerges only with difficulty.
Our noteDixon quotes Kuhn to describe the tumultuous process of scientific and logical discovery.
Rushed investment risks
As a result, founders and investors are spending very little time getting to know each other before entering into long-term business contracts. This is bad news for everyone.
Our noteDixon warns about the dangers of fast-moving financing markets where due diligence on people is skipped.
Expected Value Analysis
Building a portfolio that can deliver superior performance requires that you evaluate each investment using expected value analysis.
Our noteDixon emphasizes the importance of mathematical expectation over simple win-loss frequency.
Future of Innovation
There's a sense that all the big things have happened, but relatively speaking, nothing big has happened yet.
Our noteChris Dixon discusses how we are only at the beginning of technological change.
Depersonalizing rejection
I came to realize that employers weren't really rejecting me as a person or on my potential - they were rejecting a resume.
Our noteDixon reflects on how he handled hundreds of job rejections early in his career.
Gaming app rankings
Companies like TapJoy let you pay to get in the Top 25, and then once you are there you can get "organic" downloads by being on the toplists.
Our noteDixon explains how companies artificially inflate their app store rankings to gain organic visibility.
VC as service
VC is only partly about investing. It is primarily a service business whose purpose is to help entrepreneurs.
Our noteDixon explains that the venture capital industry is shifting toward a service-oriented model.
Strategic Product Planning
Good startups, however, think about the whole wedge from the start.
Our noteHe distinguishes between startups building random features and those with a long-term vision.
Competing with incumbents
The only way to compete is to sell used stuff or make your own products (or provide a marketplace for those things).
Our noteDixon discusses how startups can survive in a market dominated by giants like Amazon.
You are seeing 213 basic records. Membership answers from all 1,416 of this master's records.
See membershipMore masters in this field
See the whole fieldInvesting and capital allocation
These records are our compilation of public statements and sources. We are not affiliated with or endorsed by Chris Dixon or any related company. If something should come down, tell us. Takedown request form